Navigating the Evolving Landscape of Medical Malpractice Insurance
Guy Carpenter has appointed Jessica Ciak as a senior vice president to tackle the challenges in the medical malpractice insurance market. This article explores the factors driving these changes and the implications for healthcare providers.
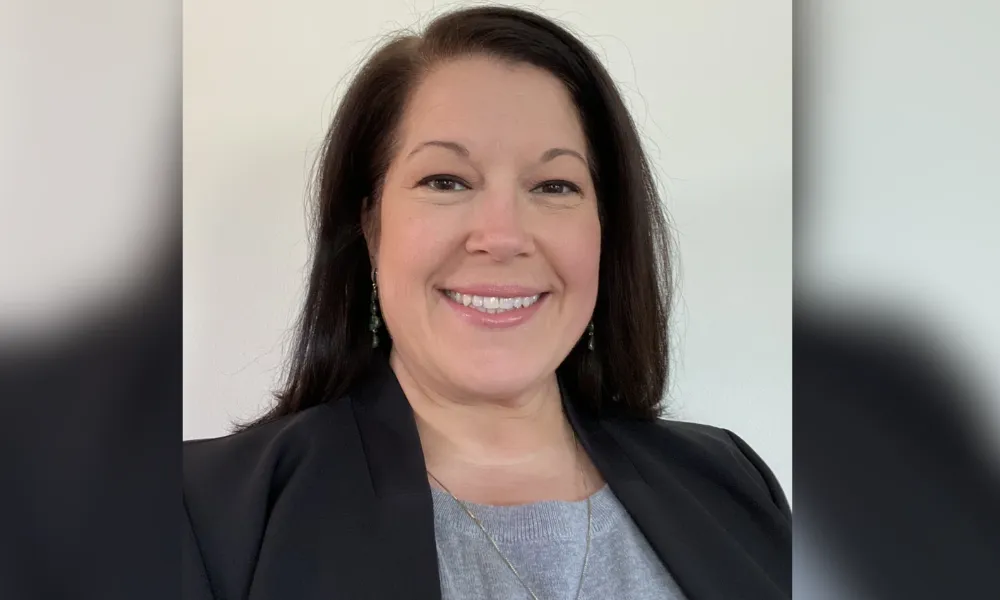
The medical malpractice insurance sector is currently undergoing significant upheaval, marked by unprecedented challenges and evolving market conditions. Recently, Guy Carpenter, a prominent global risk and reinsurance specialist, reinforced its commitment to navigating these turbulent waters by appointing Jessica Ciak as senior vice president within its Healthcare Segment. With over 25 years of experience in reinsurance, particularly in specialty lines such as medical professional liability, Ciak's expertise could not come at a more critical time for healthcare providers facing increasing legal and financial risks.
In her new role based in Minneapolis, Ciak will report directly to Martha Jacobs, the healthcare segment leader at Guy Carpenter. This strategic move signals a robust response to a volatile market characterized by record-setting verdicts and evolving legislation that favors plaintiffs. John Trace, CEO of Guy Carpenter for North America, explicitly tied Ciak's hiring to the pressing challenges clients face in the medical malpractice insurance market, highlighting the urgency to address rising severity trends and pressures on reinsurance capacity.
The Surge in Medical Malpractice Verdicts
One of the most alarming trends affecting the medical malpractice insurance landscape is the dramatic rise in the average size of jury verdicts. According to the Spring 2026 Insurance Marketplace Realities update provided by WTW, the average of the top 50 medical malpractice verdicts skyrocketed from $32 million in 2022 to an astounding $56 million in 2024—a substantial 75% increase within just two years. By early 2026, at least two individual medical professional liability verdicts had exceeded the $100 million mark, further emphasizing the severity of the situation.
This escalation in verdict amounts has compelled reinsurers to reevaluate how much aggregation risk they are willing to assume. TransRe reported a near doubling in the number of jury verdicts exceeding $10 million between the periods of 2013-2015 and 2022-2024. This shift has resulted in a more cautious approach from reinsurers, leading to tighter underwriting standards and reduced coverage limits from primary insurers.
Impact on Insurance Coverage and Pricing
The repercussions of these trends are far-reaching, affecting not only the financial stability of healthcare providers but also the structure and pricing of medical malpractice insurance. WTW's analysis indicates that many established carriers have slashed available limits significantly, with some reducing coverage from as much as $15 million to $5 million or less in certain segments of the market. This contraction in primary limits is coupled with broader modifications such as increased deductibles, extended retroactive dates, and new exclusions. As a result, there has been considerable growth in the standalone excess market, as physicians and healthcare systems seek to replenish the limits that primary carriers are increasingly reluctant to offer.
The Medical Liability Monitor’s annual rate survey has recorded an alarming trend over the past eleven years, demonstrating that the majority of medical professional liability rate filings have moved upward rather than downward, extending into the 2026 renewals. These ongoing escalations in rates and reduced limits signal that the primary market is undergoing a significant transformation.
The Role of Reinsurance in Stabilizing the Market
For carriers and Managing General Agents (MGAs) involved in writing medical professional liability, the addition of senior specialist capacity in reinsurance brokerage is indicative of the increasing complexity of placement strategies in this market. As the focus shifts to managing aggregation exposure across a cedent's entire book rather than individual policy limits, the skill set required for treaty structuring has become increasingly specialized.
This complexity underscores the vital role of experienced reinsurance intermediaries, like the one Guy Carpenter is cultivating with Ciak's appointment. For retail brokers and healthcare risk managers, the shrinking primary limits and the growing reliance on standalone excess layers highlight the critical dependence on well-capitalized reinsurers willing to support this line at scale. The effectiveness of these intermediary relationships can directly impact the extent of coverage available in the primary market, with significant implications for healthcare providers.
The Future Landscape of Medical Malpractice Insurance
As Jessica Ciak embarks on her new role at Guy Carpenter, the focus will undoubtedly be on leveraging the firm's market intelligence and placement strength to assist clients in navigating this critical period for medical professional liability. The combination of rising verdicts, tightening coverage, and evolving legal landscapes necessitates a proactive approach to risk management and insurance strategy.
Healthcare providers must remain vigilant and adaptable, exploring innovative insurance solutions and partnerships with experienced brokers to ensure they are adequately protected against these growing risks. The landscape of medical malpractice insurance is evolving rapidly, and those who fail to adapt could find themselves facing significant financial exposure.
Key Takeaways
- Record-setting verdicts: The average size of medical malpractice verdicts has risen sharply, impacting insurance pricing and availability.
- Reinsurance market shifts: Reinsurers are reassessing aggregation risks, leading to reduced coverage limits and higher premiums.
- Importance of expertise: Experienced reinsurance intermediaries are crucial in navigating the complexities of the medical malpractice insurance landscape.
- Healthcare providers must adapt: Continuous monitoring of market trends and strategic partnerships are essential for managing risk.
- Growing reliance on excess insurance: As primary limits shrink, healthcare systems increasingly depend on standalone excess policies to fill coverage gaps.
Frequently Asked Questions
What are the main factors driving the increase in medical malpractice verdicts?
The increase in medical malpractice verdicts can be attributed to a combination of factors, including evolving plaintiff-favorable legislation, heightened consumer awareness, and a growing willingness of juries to award larger compensatory sums. This shift reflects a changing societal perspective on healthcare accountability and patient rights, leading to more significant financial risks for medical professionals.
How can healthcare providers protect themselves against rising malpractice insurance costs?
Healthcare providers can take several proactive steps to mitigate the impact of rising malpractice insurance costs. These include investing in risk management training, maintaining robust documentation practices, and exploring alternative insurance structures such as captive insurance or self-insurance. Additionally, partnering with experienced insurance brokers who understand the nuances of the market can provide valuable insights and tailored solutions.
What role does reinsurance play in the medical malpractice insurance market?
Reinsurance serves as a crucial safety net for primary insurers, allowing them to spread risk and maintain solvency in the face of large claims. As the medical malpractice landscape evolves, reinsurers reassess their risk appetite, which can directly influence primary insurance offerings. A strong reinsurance market can enhance the capacity and stability of the primary insurance market, providing more options for healthcare providers.
What should providers expect in the coming years regarding malpractice insurance?
In the coming years, providers can expect continued volatility in the medical malpractice insurance market. Factors such as legislative changes, increasing claim severity, and evolving risk management practices will shape the landscape. Providers should remain adaptable and seek out innovative insurance solutions to navigate these challenges effectively.
Comments
The Shift in Pharmacy Benefits Management: Opportunities for Employers and Brokers
As employers reconsider their relationships with major pharmacy benefits managers, a significant market shift is underway. This article explores the implications for employers and brokers navigating this evolving landscape.
Related articles
Popular in Health Insurance
- Humana's Medicare Advantage Growth and Strategic Developments: Q2 2026 Insights
- FDA Calls for Enhanced Oversight in Infant Formula Supply Chain
- Abbott Laboratories Faces Cybersecurity Challenges: What It Means for Healthcare
- Surge in Cyclosporiasis Cases in Michigan: A Deep Dive into the Outbreak
- Liberty Mutual Targets New York Clinics in $1.5M No-Fault Billing Scheme Lawsuit