Court Upholds Unum's Decision to Cut Long-Term Disability Benefits
In a significant ruling, the Eighth Circuit Court has affirmed Unum's decision to terminate a worker's long-term disability benefits, citing his ability to perform sedentary work. This case highlights the complexities surrounding disability benefits and the stringent criteria that can affect claim outcomes.
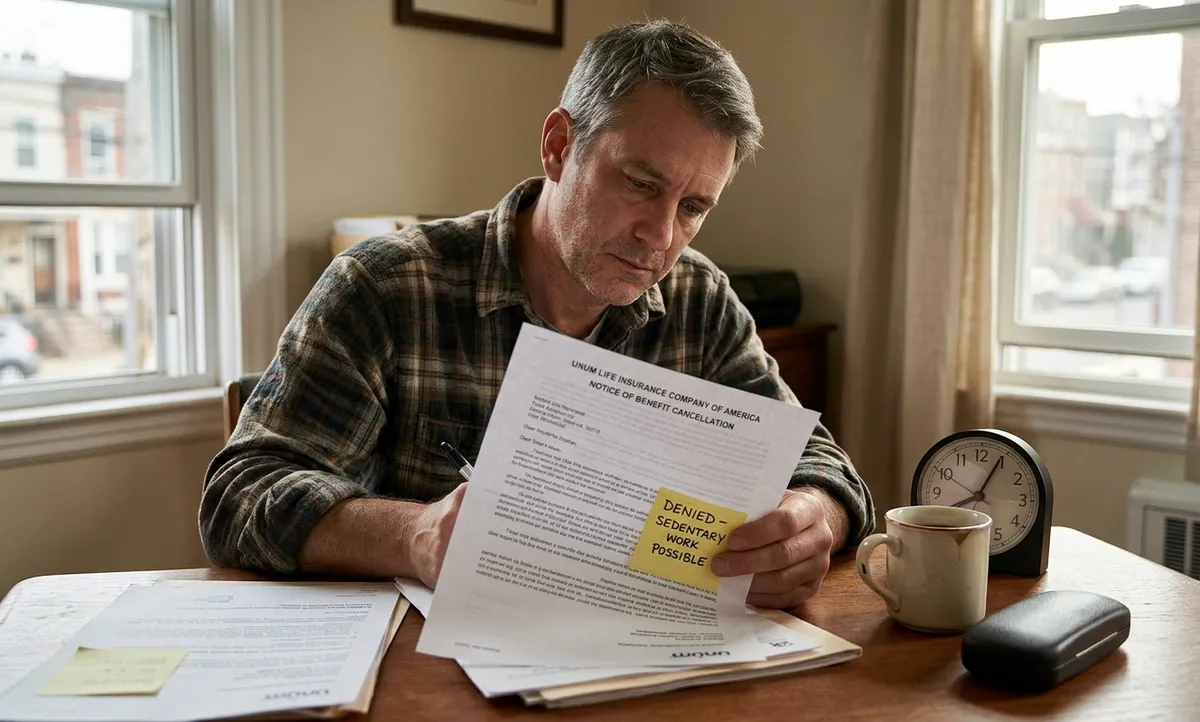
In a landmark decision impacting long-term disability benefits, the Eighth Circuit Court of Appeals recently sided with Unum Life Insurance Company of America, affirming the insurer's decision to terminate a worker's benefits based on his ability to perform sedentary work. This ruling, which came down on August 28, 2026, underscores the legal complexities surrounding disability claims and how specific plan terms can dramatically influence outcomes for policyholders.
The case revolves around a sheet metal fabricator who suffered a serious shoulder injury in October 2019, which led to surgery and a subsequent claim for disability benefits. Initially approved for short-term disability, the worker received long-term benefits starting in April 2020. However, as his condition evolved, so did the criteria for determining his eligibility for continued benefits, ultimately leading to a contentious legal battle.
Understanding the Disability Benefits Framework
Long-term disability insurance is designed to provide income replacement for individuals who are unable to work due to illness or injury. However, the specific terms and conditions of these policies can vary significantly, often affecting the duration and amount of benefits provided.
The Definition of Disability
In this case, the worker's policy included a critical distinction in its definition of “disabled.” For the first 24 months, the policy defined being disabled as the inability to perform the material and substantial duties of one’s regular occupation. After this period, the standard shifted to requiring that the individual be unable to perform the duties of “any gainful occupation” for which they are reasonably fitted by education, training, or experience. This change in definition is not uncommon and can serve as a pivotal factor in benefit determinations.
Case Details: A Timeline of Events
The worker's journey through the disability claims process began with a significant injury. An MRI revealed a full-thickness retracted rupture of the long head biceps tendon, followed by surgery in November 2019. After a brief period of recovery, Unum approved his claim for short-term disability benefits, transitioning to long-term benefits in April 2020.
Throughout the subsequent months, the worker's treating physician provided updates on his recovery. By June 2020, the surgeon indicated that the worker could handle sedentary work, which typically involves tasks performed while seated and may include light lifting. This assessment proved crucial as it directly impacted Unum's evaluation of his claim.
Shifting Standards and Claims Review
As the April 2022 deadline approached, Unum reassessed the worker's eligibility under the new definition of disability. The insurer noted that the surgeon had increased the worker's lifting limit to 20 pounds and suggested that he might need to consider a career change entirely. Following this reassessment, Unum identified alternative job roles that the worker could potentially fill, including production clerk, rental dispatcher, and routing clerk.
Ultimately, Unum terminated the worker’s benefits on April 13, 2022, citing that he was no longer precluded from performing the duties of alternative, gainful occupations. This decision sparked further disagreement, particularly when the worker's surgeon later indicated that the worker could not work at all.
The Legal Battle
Upon denial of his claim, the worker sought legal recourse, leading to a district court review. The court acted as a factfinder, determining whether the decision to terminate benefits was justified. Its findings indicated that the worker was indeed capable of sedentary work, leading to a ruling in favor of Unum.
The case was subsequently appealed to the Eighth Circuit Court, where the panel dismissed the worker's arguments against Unum's rationale. It emphasized that the insurer's reasoning had remained consistent throughout the review process and noted the absence of compelling evidence to support the surgeon's later reversal regarding the worker's restrictions.
Implications for Policyholders
This ruling serves as a stark reminder for individuals holding long-term disability insurance policies. Understanding the specific definitions and terms of your coverage is vital, as they can significantly impact your ability to secure benefits. Here are some critical considerations for policyholders:
- Know Your Definitions: Familiarize yourself with the definitions of “disability” in your policy, particularly any time limits or changes in criteria.
- Maintain Regular Medical Reviews: Keep your healthcare provider updated on your condition and ensure they provide clear documentation of your capabilities.
- Document Everything: Maintain thorough records of all communications with your insurer, including any recommendations from medical professionals.
- Consult Legal Expertise: Consider consulting with an attorney specializing in disability claims if you face a denial or termination of benefits.
Key Takeaways
- Understanding the definitions of disability in your insurance policy is crucial.
- Regular communication with healthcare providers can impact benefit eligibility.
- Documenting all interactions with insurers is essential for protecting your claim.
- Seek legal counsel when navigating complex disability claims.
Frequently Asked Questions
What should I do if my disability benefits are denied?
If your disability benefits are denied, the first step is to understand the reason behind the denial. Review the denial letter carefully and consult your policy to see if the decision aligns with the terms. Gathering additional medical documentation and possibly seeking a second opinion from your healthcare provider can also be beneficial. If you believe that the denial is unjust, you may consider appealing the decision or consulting with a legal expert specializing in disability law.
How can I prepare for a long-term disability claim?
Preparing for a long-term disability claim involves several proactive steps. Start by ensuring you have comprehensive medical documentation that clearly outlines your condition and how it impacts your ability to work. Regularly communicate with your healthcare provider, and keep records of your treatments and progress. Additionally, familiarize yourself with your policy’s definitions and requirements to ensure that you meet the eligibility criteria.
Can I work while receiving disability benefits?
Working while receiving disability benefits depends on the specifics of your policy. Many policies allow for a trial work period or partial benefits if you can perform some work. However, exceeding certain income thresholds or hours worked may jeopardize your benefits. Always check with your insurer before taking on any work to ensure you remain compliant with the terms of your policy.
Comments
Popular in Health Insurance
- Humana's Medicare Advantage Growth and Strategic Developments: Q2 2026 Insights
- FDA Calls for Enhanced Oversight in Infant Formula Supply Chain
- Abbott Laboratories Faces Cybersecurity Challenges: What It Means for Healthcare
- Surge in Cyclosporiasis Cases in Michigan: A Deep Dive into the Outbreak
- Liberty Mutual Targets New York Clinics in $1.5M No-Fault Billing Scheme Lawsuit