Vanderbilt Lawsuit Challenges Gender-Affirming Care Denials
A Vanderbilt University faculty member's lawsuit against the institution highlights critical issues surrounding insurance claim denials for gender-affirming procedures. This case may redefine employer responsibilities and protections under federal law.
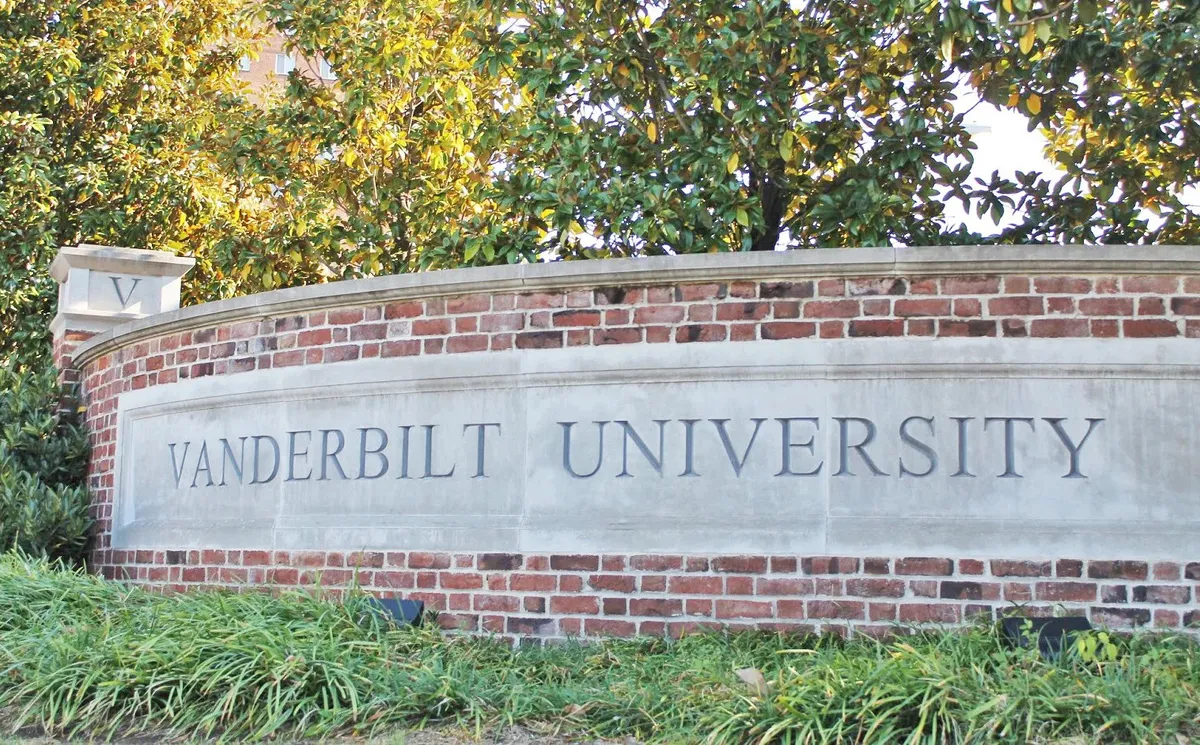
The landscape of insurance for gender-affirming procedures is evolving, but a recent lawsuit against Vanderbilt University underscores the complex interplay of employer responsibilities and patient rights. Hannah Housden, a faculty member at Vanderbilt, has filed a federal lawsuit challenging the university's denial of her insurance claim for gender-affirming facial surgery. This case raises significant questions about how self-funded employer health plans handle claims related to transgender care, particularly in light of recent legal precedents.
Housden's claim, which was denied by Aetna, the administrator of Vanderbilt's employee health plan, was rooted in the assertion that the procedure was not deemed medically necessary. Despite her appeal to Vanderbilt, the university—acting as both employer and plan administrator—upheld the denial. This dual role raises critical legal implications, particularly regarding discrimination laws under the Civil Rights Act of 1964 and the Americans with Disabilities Act (ADA).
The Legal Framework Behind the Lawsuit
Housden's lawsuit, represented by Rubenfeld Law Office, alleges that Vanderbilt discriminated against her based on her gender identity by denying her coverage for a medically necessary procedure. The complaint highlights a troubling inconsistency in Vanderbilt's employee health plan: while it covers facial procedures for various medical conditions, it explicitly excludes surgeries related to gender dysphoria.
Discriminatory Practices and Legal Precedents
This legal challenge is not occurring in a vacuum. A significant ruling in March 2026 in the case of Gordon v. Aetna Life Insurance Company established that categorical exclusions for gender-affirming surgeries could constitute sex discrimination under Section 1557 of the Affordable Care Act (ACA). The court found that insurance policies requiring a determination of a patient's transgender status before coverage could be provided were inherently discriminatory. This ruling builds on the foundational 2020 Supreme Court decision in Bostock v. Clayton County, which affirmed that discrimination based on gender identity is a form of sex discrimination.
Disparities Within Insurance Plans
One of the most striking aspects of the Vanderbilt case is the apparent inconsistency in how different plans administered by the university treat gender-affirming care. While Vanderbilt's student health plan includes coverage for facial feminization and masculinization procedures, the employee health plan specifically excludes them. This contradiction may expose the university to significant legal risk, as it creates a disparity in treatment based on gender identity.
- Coverage for facial procedures: The employee plan covers surgeries for trauma or congenital abnormalities but excludes them for gender dysphoria.
- Student plan contrast: The student health plan provides coverage for gender-affirming surgeries.
- Potential legal repercussions: Plans that exhibit such disparities may face scrutiny under discrimination laws.
Employer Responsibilities and Insurance Liabilities
The implications of this case extend beyond just Vanderbilt University. Employers who self-fund their health plans and maintain appeal authority over coverage decisions must understand their obligations under both federal law and the nuances of their specific plans. As plan administrators, they are not mere bystanders; they are responsible for the decisions made regarding coverage denials and appeals.
Understanding Self-Funded Plans
Self-funded health plans allow employers to take on the financial risk of providing health care benefits to employees. While these plans can offer flexibility, they also come with specific legal responsibilities under the Employee Retirement Income Security Act (ERISA) and the ACA. Employers must ensure that their plans do not inadvertently discriminate against employees based on gender identity, which could result in costly litigation.
The Role of State Regulations
Compounding the challenges faced by Housden and others seeking gender-affirming care is the regulatory environment in Tennessee, where the lawsuit originated. Currently, TennCare, Tennessee's Medicaid program, provides no coverage for gender-affirming care. Additionally, Vanderbilt University Medical Center ceased offering adult gender-affirming surgeries in February 2026, and a law banning gender-affirming care for minors was upheld by the Supreme Court in 2025. These state-level restrictions further complicate access to necessary medical care and highlight the urgency of providing equitable health insurance coverage.
Implications for Future Coverage and Care
As the Housden case unfolds, it may pave the way for broader protections for transgender individuals seeking medical care. Legal experts suggest that the outcome could hinge on how courts interpret the obligations of employers as plan administrators, especially in light of existing precedents regarding discrimination.
What This Means for Employers
Employers should take proactive steps to review their health plans for any discriminatory language or practices, especially those that create disparities in coverage based on gender identity. Legal experts recommend conducting a thorough audit of plan designs and consulting with insurance brokers to ensure compliance with federal and state regulations. This not only mitigates legal risks but also promotes inclusivity within the workplace.
Key Takeaways
- The Vanderbilt lawsuit highlights potential discrimination in employer health plans regarding gender-affirming care.
- Employers must understand their responsibilities under ERISA and the ACA to avoid legal liabilities.
- Disparities in coverage between employee and student plans may expose employers to discrimination claims.
- State regulations can complicate access to gender-affirming care, impacting employees’ health outcomes.
- Proactive audits of insurance plans are essential for compliance and inclusivity.
Frequently Asked Questions
What is the significance of the Vanderbilt lawsuit?
The Vanderbilt lawsuit is significant as it challenges the denial of coverage for gender-affirming care under employer health plans. It raises important legal questions about discrimination based on gender identity and the responsibilities of employers as plan administrators. The outcome could set a precedent for similar cases across the country.
How do employer health plans relate to federal discrimination laws?
Employer health plans are subject to federal discrimination laws such as the ACA and Title VII of the Civil Rights Act. These laws prohibit discrimination based on sex and gender identity, requiring employers to provide equal access to medical services. Failure to comply with these laws can result in legal action and financial repercussions.
What should employers do to ensure compliance?
Employers should conduct regular audits of their health plans to identify any discriminatory practices or language. Consulting with legal and insurance professionals can help ensure that their plans align with federal and state regulations, promoting a fair and inclusive environment for all employees.
What impact do state laws have on gender-affirming care?
State laws can significantly impact access to gender-affirming care by dictating what services are covered by Medicaid and other public health programs. In states with restrictive laws, individuals may face barriers to accessing necessary medical treatments, highlighting the importance of robust employer health plans that provide comprehensive coverage.
Comments
Rising Employer Health Benefit Costs: What to Expect by 2027
Employer health benefit costs are projected to rise by 8.2% in 2027, the highest increase in nearly 25 years. This article explores the factors driving these costs and what employers can do to manage them.
Related articles
Popular in Health Insurance
- Humana's Medicare Advantage Growth and Strategic Developments: Q2 2026 Insights
- FDA Calls for Enhanced Oversight in Infant Formula Supply Chain
- Abbott Laboratories Faces Cybersecurity Challenges: What It Means for Healthcare
- Surge in Cyclosporiasis Cases in Michigan: A Deep Dive into the Outbreak
- Liberty Mutual Targets New York Clinics in $1.5M No-Fault Billing Scheme Lawsuit