Florida Court Upholds Uninsured Motorist Coverage Despite Settlement Error
A Florida court's recent ruling emphasizes that unauthorized settlements do not automatically void uninsured motorist coverage unless the insurer can prove actual harm. This case serves as a critical reminder for both policyholders and insurers about the nuances of consent-to-settle clauses.
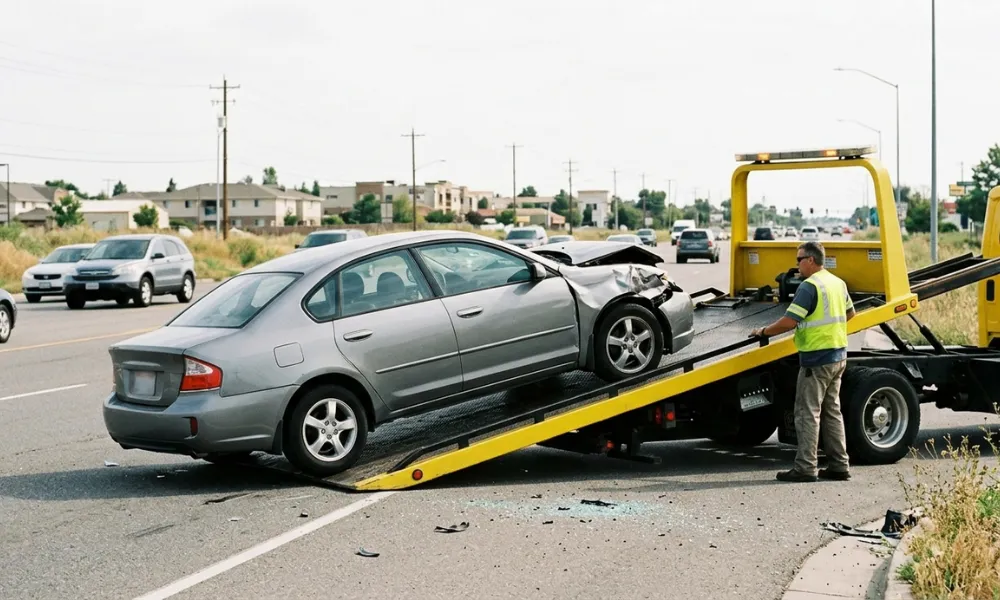
In a significant ruling for auto insurance policyholders and insurers alike, the Florida Fourth District Court of Appeal recently upheld a $500,000 uninsured/underinsured motorist (UM/UIM) policy despite a customer settling with the at-fault driver’s insurer without prior consent from Progressive. This case, decided on September 9, 2026, highlights the legal intricacies surrounding consent-to-settle clauses and the responsibilities of both parties in the claims process.
The implications of this ruling are substantial, not only for the parties directly involved but also for the broader insurance landscape. The court's decision serves as a reminder that breaking a consent-to-settle clause does not automatically void coverage unless the insurer can demonstrate actual harm. This ruling may inspire policyholders to pursue their rights more vigorously while prompting insurers to re-evaluate their strategies when dealing with unauthorized settlements.
The Incident: A Crash and an Unauthorized Settlement
The case traces back to an auto accident that transpired on April 30, 2022. The driver at fault held a mere $10,000 in liability coverage through Liberty Mutual, while the other driver, a policyholder with Progressive, had a robust $500,000 in uninsured/underinsured motorist coverage. Such policies are crucial in situations where the at-fault driver’s insurance is insufficient to cover the damages incurred.
In this instance, the Progressive policyholder, in an effort to resolve the matter expediently, signed a release and accepted the $10,000 from Liberty Mutual without obtaining Progressive’s consent—an action that would later stir contention. The policyholder’s failure to secure approval from Progressive before settling was a breach of both the policy terms and Florida law, which requires prior notification to all UM/UIM insurers before settling with the at-fault party.
Understanding Consent-to-Settle Clauses
Consent-to-settle clauses are a standard feature in many insurance policies, particularly in UM/UIM coverage. These clauses are designed to protect insurers by allowing them the opportunity to assess the settlement terms and potentially pursue recovery from the at-fault driver. In Florida, the law mandates that policyholders provide written notice of any proposed settlement via certified or registered mail, giving insurers a 30-day period to respond.
In this case, Progressive argued that the policyholder's failure to adhere to this requirement warranted the cancellation of his coverage altogether. According to Florida Statutes, such breaches could result in the loss of coverage if the insurer can prove that the breach harmed them.
Legal Proceedings and the Court's Findings
Upon realizing the mistake, the policyholder engaged new legal representation who attempted to rectify the situation. They reached out to Progressive for a waiver of its subrogation rights, which would allow the policyholder to maintain his right to claim under his UM/UIM policy. They even returned the $10,000 to Liberty Mutual in a bid to nullify the earlier settlement. However, Progressive resisted, asserting that the unauthorized settlement was grounds for rescinding the policy.
The trial court focused on whether Progressive had been prejudiced by the policyholder's actions. Florida courts begin with the presumption that an insurer suffers harm when a policyholder breaches a consent-to-settle clause. However, the burden then shifts to the policyholder to demonstrate that no actual harm occurred. In this case, the trial judge found that the at-fault driver was likely insolvent, possessing minimal financial resources and a small business that reported an income of only $20,000 annually. Given these circumstances, pursuing the at-fault driver for additional compensation would likely be futile and cost-prohibitive for Progressive.
Implications for Policyholders and Insurers
The court’s ruling hinged on the finding of “apparent and probable insolvency” of the at-fault driver, leading to the conclusion that Progressive would not have pursued subrogation even had they been properly notified of the settlement. This critical aspect of the decision underscores the importance of financial viability in assessing whether a breach has prejudiced the insurer.
This ruling has broader implications for both policyholders and insurance companies. For policyholders, it clarifies that while they must adhere to the terms of their policies, an unauthorized settlement may not necessarily result in a loss of coverage if they can prove that the insurer suffered no actual harm. For insurers, this case serves as a cautionary tale about the necessity of demonstrating true prejudice in order to void coverage—a process that can be complicated and costly.
What This Means for Future Cases
As this case illustrates, the nuanced relationship between insurers and policyholders can lead to complex legal challenges. Insurers must be diligent in their claims processes and understand the potential repercussions of allowing a policyholder to settle without consent. Conversely, policyholders should be aware of their rights and the significance of obtaining proper authorization before making any settlement decisions.
Key Takeaways
- Unauthorized Settlements: Breaching a consent-to-settle clause does not automatically void insurance coverage.
- Proving Prejudice: Insurers must demonstrate actual harm to void a policy following an unauthorized settlement.
- Financial Viability Matters: The financial condition of the at-fault driver plays a crucial role in determining whether an insurer has been prejudiced.
- Policyholder Rights: Policyholders can maintain their rights under UM/UIM coverage if they can prove no harm was done to the insurer.
- Legal Precedent: This case sets a precedent for how courts may evaluate consent-to-settle breaches in the future.
Frequently Asked Questions
What should I do if I accidentally settle without informing my insurance company?
If you find yourself in a situation where you have settled an accident claim without notifying your insurer, it is crucial to act quickly. Contact your insurance agent or representative immediately and explain the situation. They may be able to help you rectify any potential issues, such as requesting a waiver of subrogation rights or negotiating terms with the other insurer. Remember that transparency is essential; insurers are more likely to assist you if you communicate openly about your mistake.
Can my insurer deny my claim if I settled without consent?
While insurers may initially seek to deny coverage based on an unauthorized settlement, Florida law mandates that they must prove actual harm resulting from the breach. If you can demonstrate that the insurer suffered no prejudice, as evidenced by the at-fault driver’s insolvency or lack of recoverable assets, you can still pursue your claim under your policy. Legal counsel can assist in navigating this complex process.
What are the potential consequences of not following consent-to-settle requirements?
Failing to adhere to consent-to-settle requirements can lead to various consequences, including the potential loss of coverage and the inability to recover damages from your insurer. However, as highlighted by the recent court ruling, insurers must substantiate claims of prejudice before they can void a policy. Understanding these requirements can help policyholders protect their rights and avoid pitfalls when settling claims.
How can I ensure my rights are protected in the claims process?
To protect your rights during the claims process, always communicate with your insurer before making any settlement decisions. Familiarize yourself with your policy’s terms, particularly regarding consent-to-settle clauses. If you are uncertain about any aspect of the claims process, do not hesitate to seek legal advice. Being proactive and informed can significantly impact the outcome of your claims process.
Comments
Popular in Car Insurance
- Consumer Sues GEICO and LexisNexis Over Identity Theft Claims Data Error
- Addressing Self-Driving Cars' Interference with Emergency Services
- Florida Court Reverses PIP Ruling, Favoring State Farm in Key Dispute
- NHTSA Investigates Nearly 1 Million GM Vehicles for Engine Failures
- OpenRoad Insurance Expands Classic Car Coverage to 40 States