Navigating the Shifting Landscape of General Aviation Insurance
The general aviation insurance market, while appearing soft, is undergoing significant structural changes that could impact brokers, insurers, and aviation operators alike. Understanding these dynamics is crucial for navigating the complexities of pricing and risk management in this evolving space.
The general aviation insurance market may seem like a smooth ride at first glance, characterized by abundant capacity and decreasing rates across numerous segments. However, a deeper exploration reveals an intricate web of dynamics that could shape the future of this essential sector. Recent reports from WTW, a global advisory, broking, and solutions company, signal a shift that could affect everyone from aviation brokers to aircraft operators. As seasoned underwriters migrate to newly formed managing general agents (MGAs), the implications for pricing discipline and risk appetite are profound.
This seemingly soft market is marked by intense competition for well-performing accounts and a landscape where established insurers are grappling with new entrants and changing conditions. For brokers and insurers alike, understanding these underlying shifts is crucial for navigating what could be a turbulent flight ahead.
The Underwriter Migration and Its Implications
Central to the evolving landscape of general aviation insurance is the migration of experienced underwriters from established insurers to MGAs. This shift represents a significant structural change that could impact pricing and risk management strategies throughout the industry.
Understanding the Underwriter Merry-Go-Round
As identified in Gallagher’s Q3 2025 Plane Talking report, this movement of talent resembles an "underwriter merry-go-round." Underwriters who switch between established carriers often carry with them a certain level of pricing discipline, which helps stabilize rates. In contrast, those joining MGAs frequently face pressure to quickly build premium volumes. This urgency can lead to aggressive pricing strategies and a broader appetite for risk, which may destabilize the market.
Effects on Pricing and Risk Appetite
The implications of these shifts are twofold. On one hand, a surge in aggressive pricing could benefit operators seeking lower rates. On the other hand, it may lead to increased exposure for insurers, particularly if the newly underwritten risks do not perform as expected. The historical expertise that established insurers have developed over time is difficult to replace, and the companies losing out on talent face the daunting task of rebuilding that knowledge base.
Market Capacity and the Role of Delegated Authority
As new MGAs enter the market, they often utilize delegated authority structures—such as lineslips and binding authorities—to facilitate transactions. These mechanisms allow intermediaries to route substantial volumes of business through facilities rather than the open market. This shift has significant implications for the pool of risks available to direct insurers.
The Challenge for Established Insurers
For established insurers battling to maintain their premium income, the dual pressures of new entrants and the shifting landscape of delegated authority create a complicated environment. The Marsh mid-2026 aviation market pulse check echoes this sentiment, confirming that while capacity remains abundant, attritional losses are on the rise, and claims timelines are extending.
Identifying High-Risk Accounts
The disparity among account types is becoming more evident. Brokers must be particularly cautious when dealing with operators that have higher-risk profiles or significant exposure within the U.S. market. Lockton's recent launch of a dedicated U.S. aviation practice underscores the need for specialized expertise in navigating these uneven market conditions.
The Inconsistency of Long-Term Agreements
Another observation from the WTW report highlights the growing inconsistency in the execution of long-term agreements (LTAs). While LTAs have traditionally provided clients with budgetary certainty, their reliability is now in question. Insurers that previously committed to preset rate trajectories are increasingly reluctant to uphold those agreements as renewals approach. This shift creates friction and uncertainty in the renewal process.
Strategies for Brokers
Brokers are advised to engage with insurers earlier in the process to identify potential divergences that could lead to renewal surprises. Testing insurer commitment to multi-year terms is crucial to avoid pitfalls that could arise from changing market conditions or portfolio results.
Claims Trends and Market Tensions
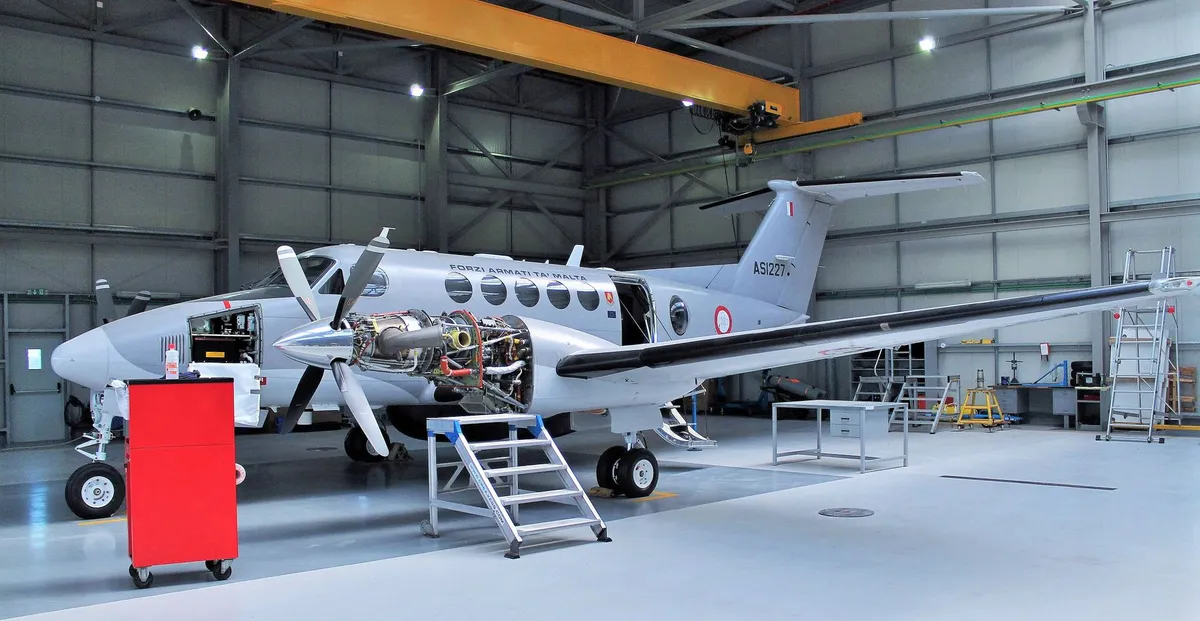
The tension within the general aviation insurance market is exacerbated by the rising costs associated with claims. Repair expenses for even minor incidents have surged by approximately 39% over the past three years. Factors like parts shortages and exclusive servicing requirements for modern engines contribute to this inflation.
The Technician Shortage
The situation is compounded by a significant shortage of certified maintenance technicians. A recent report from the Aviation Technician Education Council indicates a 10% shortage in this critical workforce, with more than a quarter of certified mechanics in North America nearing retirement age. This aging workforce accelerates repair timelines, further complicating the claims process and contributing to uncertainty in claim values.
The Gap Between Rates and Claims Costs
For insurers writing policies at reduced rates, the growing gap between declining headline rates and underlying claims inflation represents a central tension. Understanding this dynamic is essential for all stakeholders in the aviation insurance market.
Emerging Opportunities in Drones and Advanced Air Mobility
Amidst the challenges, there are also emerging opportunities in the realms of drones and advanced air mobility. Specialist MGAs have swiftly adapted to the evolving landscape, developing products tailored specifically for commercial drone operators and electric vertical takeoff and landing (eVTOL) manufacturers.
The Growth of Drone Insurance
The drone insurance market is currently experiencing a robust growth rate of approximately 10% annually, fueled by expanding applications in sectors such as logistics, agriculture, and infrastructure inspection. However, this burgeoning market is not without its challenges. Traditional actuarial models struggle to apply to eVTOL risks due to limited operational data and uncertain accident rates.
Understanding Risk in New Technologies
As underwriters navigate these new territories, they must rely on scenario analysis and benchmarking against similar technologies instead of established claims histories. This reliance on evolving data means pricing carries inherent uncertainty—an aspect that larger, well-capitalized insurers can absorb more readily than newer entrants. Brokers placing clients in drone or eVTOL programs must comprehend who is carrying that uncertainty and how it impacts pricing.
Key Takeaways
- Migration of Underwriters: Experienced underwriters are moving to MGAs, affecting pricing discipline.
- Long-Term Agreements: LTAs are becoming inconsistent; early engagement is key for brokers.
- Claims Costs: Repair costs have risen significantly, creating tension between rates and claims inflation.
- Emerging Markets: Drone insurance is growing rapidly, but underwriters face challenges in risk assessment.
Frequently Asked Questions
What does the migration of underwriters mean for the aviation insurance market?
The movement of seasoned underwriters to MGAs typically leads to a more aggressive pricing approach, which can initially benefit operators looking for lower rates. However, this shift may also increase risk exposure for insurers, potentially leading to challenges in long-term sustainability within the market.
How can brokers mitigate risks associated with long-term agreements?
Brokers should engage with insurers early in the renewal process to clarify commitments related to long-term agreements. Proactively testing an insurer's willingness to honor preset rate trajectories can help brokers manage client expectations and reduce the risk of surprises during renewals.
What are the challenges facing the drone insurance market?
The drone insurance sector is witnessing rapid growth, yet underwriters face challenges due to limited operational data and evolving technologies. This uncertainty makes it difficult to rely on traditional actuarial models, complicating risk assessment for new entrants and established players alike.
Why is the technician shortage a concern for the aviation industry?
The shortage of certified maintenance technicians is a significant concern because it leads to longer repair timelines and increased claim uncertainty. With many technicians approaching retirement and the training pipeline unable to keep pace, the aviation industry faces potential disruptions in service and increased operational risks.
Comments
Rising Risks: Aviation Insurers React to Increasing Laptop Fires
Recent laptop fires aboard American Airlines flights highlight a growing trend in aviation incidents tied to lithium batteries. With aviation insurers on high alert, what does this mean for travelers and the industry?
Related articles
Popular in Business Insurance
- Surging War-Risk Insurance Rates in the Strait of Hormuz: What It Means for Shipping
- Ross & Yerger Insurance Faces Class Action Over Data Breach Allegations
- Sompo Expands U.S. Workers' Compensation Portfolio with Service Insurance Acquisition
- Legal Battle Unfolds Over $1 Million Truck Crash Insurance Payout
- Howden Group's Ambitious Journey Toward IPO and Expansion