Usurance Insurance Company: A New Player for Asian Exporters in the U.S. Market
Usurance Insurance Company has entered the U.S. insurance market, targeting Asian exporters and businesses with cross-border operations. This article explores its offerings and the implications for the insurance landscape.
In a significant move for the insurance landscape, Usurance Insurance Company has officially launched its operations in the United States, specifically targeting Asian exporters and businesses with cross-border operations. Following its receipt of a certificate of authority from the Utah Insurance Department, effective July 30, Usurance is poised to fill a critical gap in the insurance market for Asian-American business owners and international companies looking to navigate the complexities of U.S. insurance. With a focus on property, liability, vehicle liability, and marine and transportation insurance, Usurance aims to offer tailored coverage solutions where traditional insurance carriers have often hesitated.
Founded by Charles Huang, a seasoned executive with a background in private equity and securities analysis, Usurance is positioned at the intersection of cultural understanding and specialized insurance needs. Huang’s vision, supported by his firm Pasaca Capital, not only caters to the unique challenges faced by Asian exporters but also addresses the evolving needs of the U.S. insurance market. This article delves into the specifics of Usurance's offerings, its target sectors, and the broader implications for Asian businesses operating in the U.S. and for the insurance industry as a whole.
Filling a Critical Gap in the Insurance Market
Historically, Asian companies exporting goods to the U.S. have encountered significant hurdles when seeking adequate insurance coverage. Many standard admitted carriers are reluctant to underwrite these businesses due to various factors, including a lack of familiarity with Asian supply chains, language barriers, and the complexities surrounding product liability insurance that meets U.S. standards. As a result, many of these businesses have found themselves moving towards the Excess and Surplus (E&S) market, where they lose access to state guaranty fund protections and statutory consumer protections that admitted coverage provides.
Usurance positions itself as a solution to these challenges by leveraging its multilingual capabilities and a deep understanding of Asian business culture. By doing so, it aims to create an environment where Asian exporters can confidently obtain the coverage they need. The company’s stated target sectors include:
- Product Liability: Protecting manufacturers and distributors against claims related to product defects.
- Logistics: Offering coverage for goods in transit, addressing the unique risks associated with shipping.
- Aviation Insurance: Covering aircraft operations, which can be particularly complex for international businesses.
- Intellectual Property: Safeguarding innovations and trademarks against infringement.
The Challenge of Wildfire Risks in California
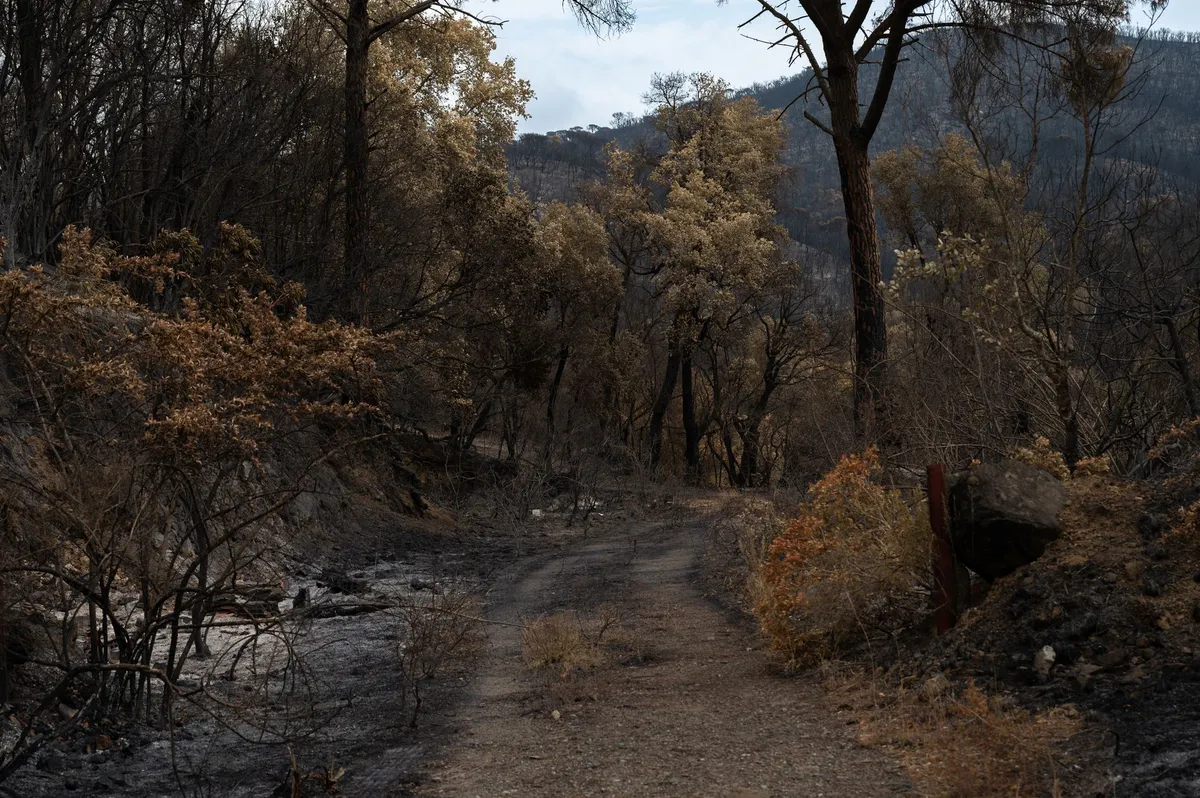
Another area of focus for Usurance is fire-risk residential property, particularly in regions like California that have faced increased wildfire incidents. The admitted insurance market in California has been contracting due to rising wildfire losses and regulatory constraints on rate adequacy. This has led to a surge in enrollment in the California FAIR Plan, which provides coverage to high-risk properties but often lacks comprehensive solutions.
Huang has identified wildfire-impacted property as a priority for Usurance, emphasizing the need for “comprehensive insurance coverage and multiple customized solutions” for Utah residents and businesses affected by wildfires. As wildfires continue to pose a significant threat, the need for innovative insurance solutions that address these risks is more pressing than ever.
The Path Ahead: Licensing and Market Expansion
While Usurance has made a promising entrance into the Utah market, it is important to note that the company’s geographic expansion will require separate licensing in each additional jurisdiction. Currently, Usurance has not disclosed a pipeline or timeline for further licensing, which could impact its growth trajectory. As the company seeks to broaden its reach, it will need to navigate the complexities of state insurance regulations, which vary significantly across the U.S.
Moreover, the absence of an AM Best financial strength rating raises concerns for brokers and clients alike. Many brokers require a certain rating for placement recommendations, particularly when working with new carriers. Without a clear indication of Usurance's financial strength, brokers may need to conduct thorough due diligence before recommending Usurance to clients. This includes confirming the current status of its Utah licensing, understanding the specific lines and limits available for different risks, and ensuring that adequate capital and claims-paying capacity are in place.
The Role of Technology in Usurance's Operations
As part of its launch, Usurance has highlighted its reliance on AI-assisted capabilities to enhance customer communications, claims document review, and multilingual administration. While these technological advancements promise to streamline processes and improve efficiency, the company has not provided a concrete implementation timeline for these features. For brokers and clients, understanding how these technologies will be integrated into Usurance’s operations will be crucial for assessing its long-term viability.
Key Takeaways
- Usurance Insurance Company is the first U.S.-licensed insurer with Chinese heritage, focusing on Asian exporters.
- It aims to address significant gaps in coverage for product liability, logistics, aviation, and intellectual property.
- The company is prioritizing wildfire-risk property coverage in Utah amid California's tightening insurance market.
- Broker diligence is essential, given the absence of an AM Best rating and the need for separate state licenses.
- Usurance's use of AI technology could enhance operational efficiency, but timelines remain unclear.
Frequently Asked Questions
What types of insurance does Usurance offer?
Usurance offers a range of insurance products, including property, liability, vehicle liability, and marine and transportation insurance. It particularly focuses on sectors that serve Asian exporters and businesses with cross-border operations, such as product liability and logistics insurance.
Why is Usurance significant for Asian exporters in the U.S.?
Usurance’s entry into the U.S. market is significant because it addresses the longstanding challenges that Asian exporters have faced in obtaining adequate insurance coverage. By leveraging its multilingual capabilities and understanding of Asian business culture, Usurance aims to provide tailored solutions that traditional insurers have been hesitant to offer.
What challenges does Usurance face in expanding its market presence?
One of the primary challenges Usurance faces is obtaining the necessary licenses to operate in additional states, as each state has its own regulatory requirements. Additionally, the company’s absence of an AM Best financial strength rating could hinder its ability to attract brokers and clients who typically rely on such ratings for underwriting decisions.
How does Usurance plan to integrate technology into its operations?
Usurance has mentioned the use of AI-assisted capabilities to improve customer interactions, claims processing, and multilingual support. However, the company has yet to provide a specific timeline for when these technologies will be fully implemented, leaving stakeholders eager for updates on this aspect of its operations.
Comments
Rising Blackout Risks Amidst Extreme Heat: A National Concern
As intense heat waves push electricity grids to their limits, the risk of blackouts looms larger across the U.S. This article explores the implications of this situation for consumers and businesses alike.
Related articles
Popular in Business Insurance
- Surging War-Risk Insurance Rates in the Strait of Hormuz: What It Means for Shipping
- Ross & Yerger Insurance Faces Class Action Over Data Breach Allegations
- Sompo Expands U.S. Workers' Compensation Portfolio with Service Insurance Acquisition
- Legal Battle Unfolds Over $1 Million Truck Crash Insurance Payout
- Howden Group's Ambitious Journey Toward IPO and Expansion