How 9/11 Reshaped American Insurance: A Quarter-Century Later
The Terrorism Risk Insurance Program (TRIP) has been extended through 2034, highlighting the enduring impact of 9/11 on the insurance landscape. This article explores the significant changes in insurance policies, risk assessments, and market dynamics stemming from the tragic events of September 11, 2001.
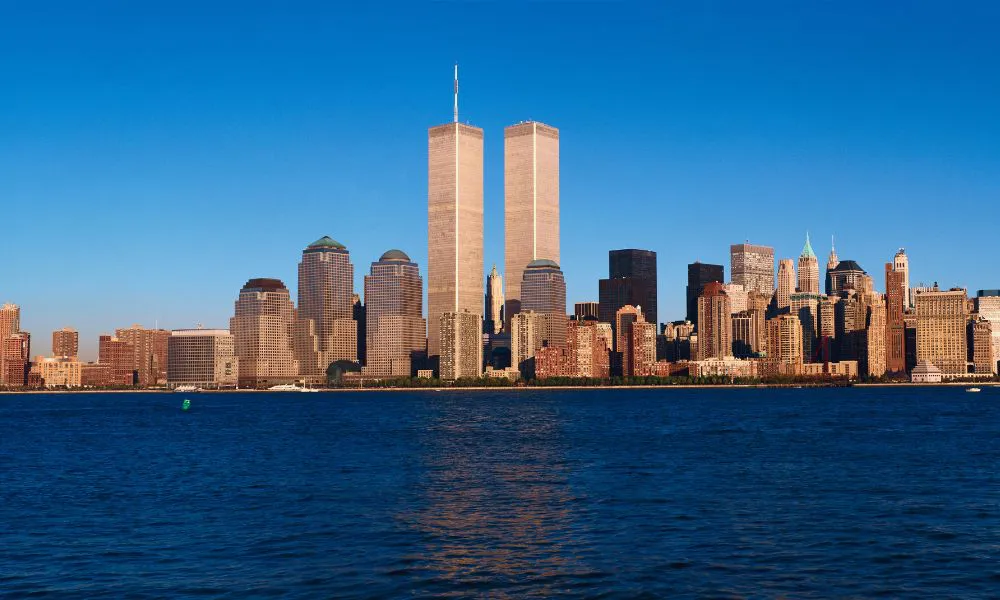
The devastating events of September 11, 2001, not only claimed nearly 3,000 lives but also fundamentally altered the landscape of American insurance. As the US House of Representatives recently voted to extend the Terrorism Risk Insurance Program (TRIP) through 2034, it's essential to reflect on the profound changes initiated by that tragic day. The mechanisms and policies put in place in the aftermath of 9/11 continue to influence how insurers assess risk, structure policies, and interact with the government, revealing the far-reaching legacy of that fateful morning.
As we delve into this complex topic, it becomes evident that the ramifications of 9/11 extended well beyond immediate losses. The resolution of contentious legal battles, the establishment of compensation frameworks, and the evolution of commercial underwriting practices demonstrate how an unprecedented crisis can lead to significant regulatory and market shifts. Understanding these developments is crucial not just for industry professionals but for consumers who rely on the stability and predictability of their insurance coverage.
The Birth of the Terrorism Risk Insurance Program
In the wake of 9/11, Congress acted swiftly to address the immediate fallout from the attacks. On September 22, 2001, just eleven days after the tragedy, lawmakers passed the Air Transportation Safety and System Stabilization Act. This legislation was designed to provide much-needed financial relief to airlines, capping their liability for the crashes at the amount of insurance they already held. This cap, estimated at approximately $6 billion for the four aircraft involved, aimed to prevent a catastrophic financial collapse in the aviation sector.
But the broader implications of the attacks reached far beyond the airline industry. By 2002, commercial insurers found themselves grappling with the reality that they could no longer secure reinsurance for terrorism-related risks. This inability to transfer risk created a chilling effect on real estate lending; banks were reluctant to extend credit for properties without adequate coverage against potential terrorist attacks. In response to this crisis, Congress enacted the Terrorism Risk Insurance Act (TRIA) of 2002. This landmark legislation established a federal backstop that enabled the government to share losses from certified terrorist acts with private insurers once losses surpassed a specified threshold—currently set at $58.7 billion.
The Functionality of TRIP
TRIP has become an essential component of the American insurance ecosystem, allowing insurers to underwrite policies that include terrorism coverage without excessive risk exposure. Despite its implementation nearly 25 years ago, the program has not yet triggered any payouts for certified acts of terrorism, a fact that speaks to its effectiveness in stabilizing the market. In a recent statement, Representative Mike Flood, who sponsored the latest reauthorization bill, emphasized the need for updates to the program to ensure taxpayer protections in light of potential future claims.
The Legal Landscape Post-9/11
The aftermath of 9/11 also left an indelible mark on the legal framework governing insurance coverage. A particularly notable case arose from the World Trade Center property insurance claims, where the leaseholder, Larry Silverstein, had bound coverage just weeks prior to the attacks. The question of whether the two aircraft strikes constituted one or two separate insured occurrences became the crux of a contentious legal battle. In 2004, one jury found that the strikes counted as a single occurrence, while another found that they were indeed two separate events, leading to a nearly doubled payout for Silverstein. This split decision was upheld by the Second Circuit Court in 2006 and continues to serve as a reference point in coverage disputes regarding the definition of a single occurrence.
Impact on Underwriting Practices
This legal uncertainty prompted a shift in market behavior, with insurers tightening their underwriting practices. Insurance professionals became more cautious about binding coverage informally and delaying the finalization of policy wording, a habit that had previously been commonplace. As a result, the insurance industry has evolved to prioritize clearer definitions and greater precision in policy language.
Current Market Conditions and Future Risks
Fast forward to the present day, and the landscape of terrorism insurance stands in stark contrast to the days immediately following 9/11. Remarkably, the absence of any payouts under TRIP has contributed to a decline in terrorism insurance premiums. According to Willis's US Terrorism Insurance Index, premiums for standalone terrorism coverage dropped by an average of 10.4% in the fourth quarter of 2025. The current capacity for US terrorism coverage has grown to over $2 billion, yet the ongoing geopolitical instability raises concerns among underwriters regarding the sustainability of these low premiums.
A Parallel with Cyber Insurance
Interestingly, the current dynamics in the terrorism insurance market mirror those in the cyber insurance sector. Just as the insurance industry faced challenges modeling the risks associated with terrorism in the wake of 9/11, it now grapples with the complexities of cyber threats. The emergence of AI-enabled attacks and state-sponsored cyber warfare have created a chaotic environment where losses can cascade through numerous unrelated policyholders, complicating underwriting and pricing efforts. Although the idea of a federal backstop for cyber risks has been proposed, it remains unimplemented, leaving the industry to navigate these volatile waters on its own.
Key Takeaways
- TRIP has been extended through 2034, highlighting its importance in stabilizing the insurance market post-9/11.
- The program has not triggered any payouts in its 24-year history, reflecting its effectiveness.
- Legal battles over coverage definitions have led to stricter underwriting practices in the insurance industry.
- Current terrorism insurance premiums are declining despite geopolitical instability, raising concerns for underwriters.
- Cyber insurance faces similar challenges in modeling risks, with no federal backstop in place.
Frequently Asked Questions
What is the Terrorism Risk Insurance Program (TRIP)?
The Terrorism Risk Insurance Program (TRIP) is a federal program established to provide a backstop for insurers against catastrophic losses resulting from terrorist attacks. It was created in the aftermath of the September 11 attacks to stabilize the insurance market and enable insurers to offer terrorism coverage without bearing excessive risk. The program shares losses between the federal government and private insurers once losses exceed a predetermined threshold, currently set at $58.7 billion for 2026.
Why has TRIP never triggered a payout?
TRIP has not triggered any payouts in its 24-year history primarily because no certified act of terrorism has resulted in losses exceeding the established threshold. This absence of claims demonstrates the program's effectiveness in stabilizing the insurance market. It also reflects the industry's ability to manage risks associated with terrorism, despite the ongoing geopolitical tensions that continue to pose potential threats.
What impact did 9/11 have on insurance underwriting practices?
The events of 9/11 led to significant changes in insurance underwriting practices, particularly in the realm of terrorism coverage. The legal disputes surrounding the World Trade Center insurance claims prompted insurers to adopt stricter standards and clearer definitions in policy language. Insurers became more cautious about binding coverage informally and delaying the finalization of policy wording, which had been common practice before the attacks. This shift toward tighter underwriting discipline has persisted in the industry.
How does the current landscape of terrorism insurance compare to cyber insurance?
The current landscape of terrorism insurance shares similarities with the cyber insurance market in that both sectors face challenges in modeling risks associated with catastrophic events. Just as underwriters struggled to price terrorism risk after 9/11 due to the lack of historical data, they are now grappling with the complexities of cyber threats, where losses can rapidly cascade through multiple unrelated policyholders. While there have been calls for a federal backstop for cyber risks, no such mechanism has been established, leaving insurers to navigate these uncertainties independently.
Comments
Pooled Employer Plans Surge: A New Era for Small Businesses
The pooled employer plan (PEP) market has dramatically expanded, exceeding $34 billion in assets as small employers increasingly adopt this innovative retirement solution. This article explores the implications of this growth for employers and the landscape of retirement planning.
Related articles
Popular in Business Insurance
- Surging War-Risk Insurance Rates in the Strait of Hormuz: What It Means for Shipping
- Ross & Yerger Insurance Faces Class Action Over Data Breach Allegations
- Sompo Expands U.S. Workers' Compensation Portfolio with Service Insurance Acquisition
- Legal Battle Unfolds Over $1 Million Truck Crash Insurance Payout
- Howden Group's Ambitious Journey Toward IPO and Expansion