Admiral Insurance vs. CUMIS: A Legal Battle Over Defense Costs
Admiral Insurance has taken legal action against CUMIS Insurance, seeking reimbursement for defense costs in a worker's injury case involving the State of New York. This article explores the implications of this case and how it impacts insurers and policyholders alike.
The insurance industry is often a complex web of policies, liability, and legal obligations. Recently, Admiral Insurance Company has found itself embroiled in a significant legal battle against CUMIS Insurance Society, Inc., stemming from a worker's injury case in New York State. This lawsuit, filed in the U.S. District Court for the Western District of New York, raises critical questions about the responsibilities of insurance companies when it comes to defending clients against claims and the nuances of policy coverage. It highlights not only the intricacies of the insurance world but also the potential impact on policyholders and businesses reliant on comprehensive coverage.
On September 10, 2026, Admiral Insurance initiated the lawsuit, seeking a judicial declaration that CUMIS must assume primary responsibility for defending the State in an ongoing worker's compensation claim. This case, which involves allegations of negligence against the State of New York—specifically Buffalo State College—demonstrates the interconnected relationships between different insurance providers and the complexities that arise when multiple policies are in play.
The Background of the Dispute
The conflict centers around Elmer W. Davis, Inc., a roofing contractor insured by both Admiral and CUMIS. Admiral holds the contractor's commercial general liability (CGL) policy, while CUMIS provides the commercial auto policy. Under the terms of their contract with the State, both insurers had agreed to cover the State as an additional insured party, effectively allowing the State to access coverage under both policies when needed. However, the nature of the coverage was specified as primary and noncontributory, which means that CUMIS was to be the first line of defense in any claims involving the State.
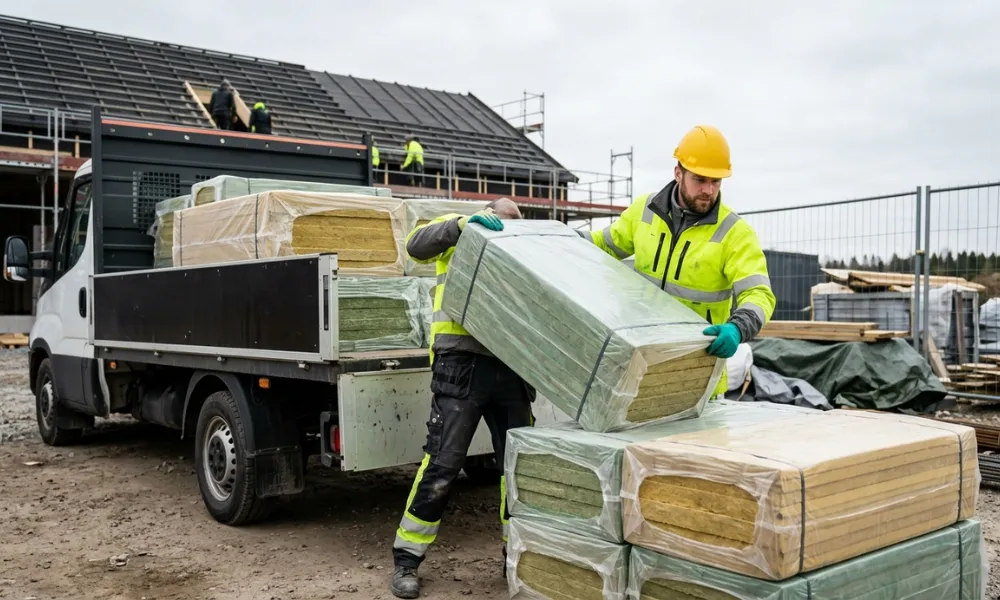
The underlying incident occurred during a roofing project when a construction worker was reportedly injured after being struck by an unsecured bundle of insulation that fell while unloading a truck. The worker subsequently filed a lawsuit against the State under New York Labor Law, a move that has yet to see resolution. Notably, the worker’s medical expenses are approximately $10,000, while the auto policy issued by CUMIS carries a liability limit of $1 million.
Admiral’s Position: Seeking Reimbursement
Initially, Admiral agreed to defend the State under its liability policy, albeit with a reservation of rights, meaning it could later contest its obligation to provide coverage. However, upon discovering that the incident involved a vehicle owned by the roofing contractor and covered under CUMIS’s auto policy, Admiral transferred the defense responsibility to CUMIS. This decision was based on a recognition that the case involved auto liability rather than a general liability risk.
Despite acknowledging the applicability of its policy, CUMIS has since refused to reimburse Admiral for the defense costs already incurred, amounting to $65,496.28. CUMIS characterized these payments as “voluntary,” citing an auto exclusion in Admiral’s liability policy as justification for denying reimbursement. Furthermore, CUMIS has indicated plans to examine whether Admiral complied with New York’s insurance law regarding denial of coverage, particularly Section 3420(d)(2).
Legal Implications and Insurance Regulations
This lawsuit brings to light several legal nuances that can have far-reaching effects on the insurance industry. The crux of Admiral's claims is threefold:
- **CUMIS must provide a defense for the State on a primary and noncontributory basis.** This means that CUMIS is obligated to lead the defense, not merely contribute after Admiral has paid out.
- **CUMIS must indemnify the State based on the same principles.** This reinforces the obligation to cover any potential damages awarded in the underlying lawsuit.
- **CUMIS must reimburse Admiral through equitable subrogation.** This legal principle allows Admiral to step into the shoes of the State to recover costs that another insurer should rightfully pay.
While these claims are currently untested in court, the outcome could set important precedents for how insurers interpret their coverage obligations. In New York, insurance laws dictate specific behaviors and responsibilities, particularly when it comes to the defense of insured parties. The nuances of these regulations can significantly impact how claims are managed and how costs are allocated between insurers.
Who is Affected by This Case?
The ramifications of this case extend beyond the two insurers involved. For contractors and businesses that rely on comprehensive insurance coverage, the outcome could influence premium rates and the availability of certain policy types. If CUMIS is ultimately required to reimburse Admiral, it could lead to increased scrutiny of coverage terms and exclusions in commercial auto policies.
Moreover, the case also underscores the importance of understanding the insurance landscape for all parties involved—contractors, insurers, and clients alike. As businesses navigate their insurance options, they must be aware of how different policies interact, especially when additional insured parties are involved. The potential financial strain on Admiral, which is currently absorbing defense costs, is a wake-up call for many in the industry to reassess their coverage strategies.
Looking Ahead: What’s Next?
As this legal battle unfolds, all eyes will be on the court's ruling regarding Admiral's claims against CUMIS. The decision will not only dictate the financial responsibilities of both insurers but also potentially reshape the dynamics of how insurance policies are structured in the construction industry and beyond. Insurers may find themselves reevaluating their coverage agreements and clarifying the terms under which they will defend additional insureds.
For policyholders, this case serves as a reminder of the complexities involved in insurance coverage and the critical importance of understanding policy terms. As businesses face various risks, clarity in coverage can make a significant difference in mitigating financial exposure.
Key Takeaways
- Admiral Insurance is suing CUMIS over defense costs related to a worker injury case.
- The dispute involves complex insurance terms such as primary and noncontributory coverage.
- The outcome could influence insurance practices and costs for contractors and businesses.
- Understanding policy interactions is crucial for businesses to mitigate risks.
- The case highlights the importance of clarity in insurance agreements.
Frequently Asked Questions
What does primary and noncontributory coverage mean?
Primary and noncontributory coverage refers to a situation where one insurer is designated to pay first for any claims before other insurance policies come into play. In this context, it means that CUMIS, as the auto insurer, is responsible for covering the State’s defense and any related costs before any contributions from Admiral’s general liability policy, which is significant in determining how claims are settled.
How could the outcome of this case affect insurance premiums?
If the court finds in favor of Admiral, it may signal to insurers that they need to be more forthcoming in their defense obligations, potentially leading to adjustments in how policies are priced. Insurers might raise premiums to account for the increased risk of having to cover defense costs for additional insureds, which could ultimately affect businesses purchasing such coverage.
What should policyholders consider when selecting insurance coverage?
Policyholders should thoroughly understand the terms of their insurance policies, especially regarding additional insured provisions and the interplay between different types of coverage. It's crucial to assess how these policies will respond in the event of a claim, as well as the potential liabilities they may face. Consulting with an insurance professional can also help clarify complex terms and ensure adequate protection.
Can this case set a precedent for future insurance disputes?
Yes, the outcome of this case could establish important legal precedents regarding the duties of insurers when it comes to defending additional insured parties. A ruling in favor of Admiral could encourage more comprehensive coverage terms and create a framework for handling similar disputes in the future, impacting how insurers draft their policies and manage claims.
Comments
Hess vs. National Interstate: A Legal Battle Over Insurance Coverage
Hess Energy has filed a lawsuit against National Interstate Insurance, alleging that the insurer failed to provide coverage for cancer lawsuits stemming from employee exposure to hazardous materials. This article delves into the implications of the case, the insurance dynamics at play, and what it means for companies seeking coverage.
Related articles
Popular in Business Insurance
- Surging War-Risk Insurance Rates in the Strait of Hormuz: What It Means for Shipping
- Ross & Yerger Insurance Faces Class Action Over Data Breach Allegations
- Sompo Expands U.S. Workers' Compensation Portfolio with Service Insurance Acquisition
- Legal Battle Unfolds Over $1 Million Truck Crash Insurance Payout
- Howden Group's Ambitious Journey Toward IPO and Expansion