Coliving Rentals: Navigating the Insurance Gap in a Growing Market
As coliving spaces gain popularity, the insurance market struggles to adapt. This article explores the challenges and solutions for insuring coliving arrangements, highlighting key insights for investors and tenants.
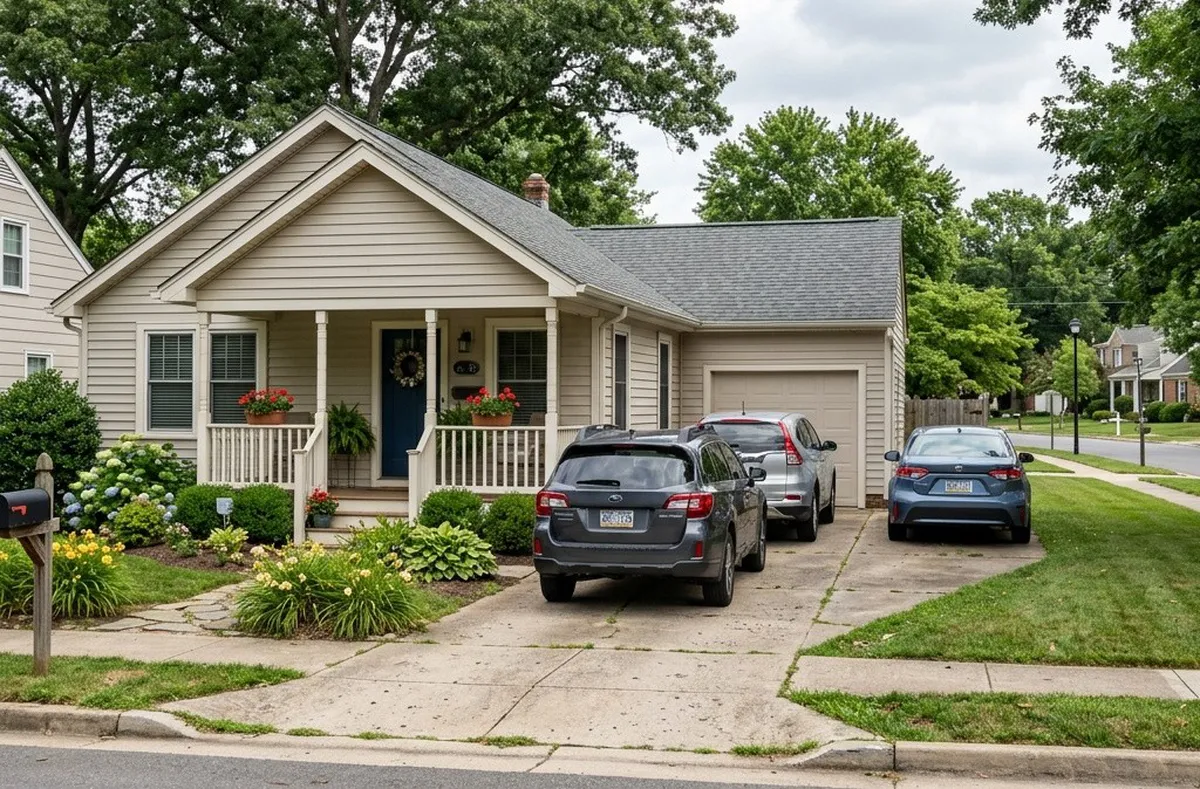
The coliving rental model, characterized by multiple tenants sharing a single property with separate leases, is rapidly gaining traction across the United States. While this innovative housing solution offers financial benefits for landlords and affordability options for renters, it is simultaneously posing significant challenges for the insurance market. Traditional insurance policies, designed for conventional landlord-tenant arrangements, often fall short in addressing the unique risks associated with coliving. As demand for coliving spaces rises, understanding the insurance landscape becomes crucial for both investors and tenants alike.
In recent years, the coliving sector has emerged as a viable solution for urban housing challenges, driven by escalating housing costs and changing lifestyle preferences. Investors are attracted to the potential for increased rental income through room-by-room leasing, while tenants are opting for coliving arrangements as a more affordable alternative to traditional renting. However, this shift disrupts long-standing insurance frameworks, leading to gaps in coverage that could leave both property owners and tenants vulnerable.
The Coliving Model: A New Housing Paradigm
Coliving spaces typically cater to a diverse group of tenants who share common areas such as kitchens and living rooms while maintaining individual leases for their private rooms. This arrangement is particularly appealing in urban environments where housing costs are high, and the demand for affordable living options is increasing. As reported by Everything Coliving, leasing a four-bedroom home by the room can generate up to $2,400 per month—substantially higher than the $2,000 average for a single household lease.
Market Dynamics Driving Coliving
The surge in coliving popularity can be attributed to several factors:
- Affordability: With rising rental prices, many tenants are opting for shared living situations to reduce costs.
- Flexibility: Coliving arrangements often come with flexible lease terms, appealing to younger tenants who prioritize mobility.
- Community Living: Many coliving spaces foster a sense of community, attracting individuals looking for social interaction in an urban setting.
According to market analysis, the US coliving market was valued at approximately $1.65 billion in 2025 and is projected to reach $3.5 billion by 2031. This rapid growth underscores the need for a corresponding evolution in the insurance landscape to accommodate the unique risks presented by this model.
The Insurance Gap: Risks and Challenges
As coliving arrangements proliferate, traditional insurance policies are often inadequate to cover the complexities of shared living. Standard landlord or dwelling policies were designed for a conventional occupancy model with clear liability relationships—one tenant or household per lease. However, the rent-by-the-room model complicates these assumptions, leading to questions about liability and coverage in the event of a claim.
Common Scenarios and Liability Issues
In a coliving environment, several liability scenarios pose challenges:
- Property Damage: If a cooking fire caused by one tenant damages another tenant's room or shared spaces, determining coverage can be complex.
- Injury Claims: If a guest slips and falls in a common area, questions arise about which lease governs liability and who is responsible for the damages.
- Shared Responsibility: The lack of clarity in liability relationships can lead to disputes among tenants and property owners regarding coverage.
Despite the increasing demand for coliving spaces, many insurers remain hesitant to underwrite these risks. The National Association of Insurance Commissioners has indicated that most standard homeowners and dwelling policies do not adequately address claims involving paying tenants, which can result in coverage denials even in the absence of explicit exclusions.
Emerging Solutions: Specialized Insurance Products
In response to the growing coliving market, specialized insurance providers are beginning to develop products tailored to the unique risks associated with this model. REInsurePro, a Kansas City-based program manager, has launched a Rent-by-the-Room package specifically designed to address coliving risks. This innovative product includes coverage for dwelling, premises liability, and tenant liability, providing a comprehensive solution for property owners.
Key Features of the Rent-by-the-Room Package
This specialized insurance product offers several benefits:
- Tenant Liability Coverage: The package transfers losses caused by an at-fault tenant back to that tenant, protecting property owners from absorbing claims arising from roommate conduct.
- $60,000 Limit: Each location is covered up to $60,000, providing a safety net for property investors.
- Independent Agents: The product is available through appointed independent agents, allowing for personalized service and guidance.
However, it is important to note that this product is not universally available. Certain states and cities, including California, Colorado, New York, Chicago, Houston, Miami, and Philadelphia, are excluded from coverage, which represents a significant portion of the coliving market. Investors in these areas must seek alternative solutions, as the REInsurePro product does not address their needs.
Understanding the Broader Insurance Landscape
The ongoing challenges faced by the coliving sector reflect a broader trend within the insurance industry. As highlighted in Marsh McLennan's Real Estate Risk and Resilience report, the shift towards specialty program managers catering to residential investment risks represents a structural change in how these properties are insured. Traditional carriers have largely exited this space, leaving a significant gap that specialized providers are now stepping in to fill.
Implications for Investors and Tenants
For investors and property owners, understanding the insurance landscape is essential. As coliving spaces continue to grow in popularity, ensuring adequate coverage will be vital to mitigating risks associated with shared living. Tenants, too, must be aware of the implications of their living arrangements and the potential for liability claims that could arise.
Key Takeaways
- The coliving rental model is rapidly growing, driven by affordability and community living.
- Traditional insurance policies are often inadequate for the unique risks associated with coliving.
- Specialized insurance products, like the Rent-by-the-Room package, are emerging to address these gaps.
- Investors should be aware of state-specific exclusions when seeking coverage for coliving properties.
- The insurance landscape is evolving, reflecting broader trends in residential investment risks.
Frequently Asked Questions
What is coliving and why is it becoming popular?
Coliving is a housing model where individuals share a living space, such as a house or apartment, while maintaining private bedrooms under separate leases. This arrangement has gained popularity due to rising housing costs, particularly in urban areas, where many individuals are seeking more affordable living options. The community aspect of coliving also appeals to younger tenants who value social interaction.
What are the insurance challenges associated with coliving spaces?
Coliving spaces present unique insurance challenges due to the multiple tenants sharing common areas and separate leases. Traditional insurance policies often do not cover the complexities of shared living, leading to potential gaps in liability coverage. Common issues include determining liability for property damage or injury claims that occur in shared spaces.
What types of insurance products are available for coliving arrangements?
Specialized insurance products, such as the Rent-by-the-Room package from REInsurePro, have been developed to address the unique risks of coliving environments. These products typically include coverage for dwelling, premises liability, and tenant liability, providing comprehensive protection for property owners. However, availability may vary by state and city, so investors should research options carefully.
How can investors and tenants protect themselves in coliving arrangements?
Investors can protect themselves by seeking specialized insurance coverage tailored to coliving risks and ensuring they understand the specifics of their policy, including any exclusions. Tenants should also be aware of the potential for liability claims and ensure they have their own renters' insurance for personal belongings and liability coverage. Open communication among tenants regarding house rules and responsibilities can also help mitigate risks.
Comments
Wildfire Risks and Hidden Dangers: The Buried Ordnance Challenge in Europe
As wildfires rage across Europe, the discovery of buried World War ordnance complicates firefighting efforts. This situation raises critical questions about wildfire management and property insurance in the U.S.
Related articles
Popular in Home Insurance
- 2026 Sees Below-Average Severe Convective Storm Losses: What It Means for Insurance
- El Niño and Wildfires: Preparing for a Fire-Prone Future
- Young Affluent Collectors: The Underinsurance Dilemma in Luxury Investments
- Wisconsin Property Owner Sues City and Insurers Over Contamination Cleanup Costs
- Rising Catastrophe Risks: How Europe’s Insurers Are Adapting to Climate Change