Florida's Citizens Insurance Cuts Policies: What Homeowners Need to Know
Citizens Property Insurance is drastically reducing its policy count, affecting thousands of Florida homeowners. Brokers must navigate the changing landscape as clients seek new coverage options.
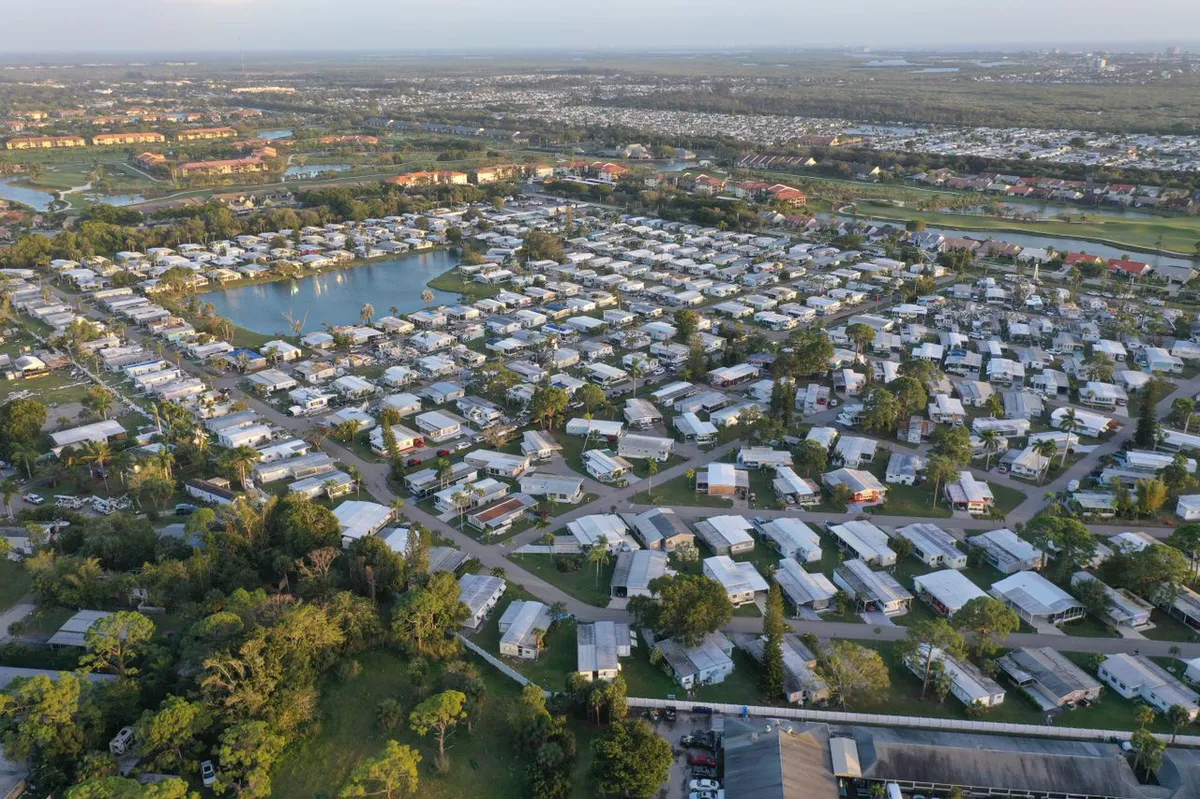
In a strategic move to stabilize Florida’s tumultuous property insurance market, Citizens Property Insurance Corporation, the state-backed insurer of last resort, has initiated a significant reduction in its policy count. After reaching a staggering peak of approximately 1.4 million policies in September 2023, Citizens has recently sent out 45,000 non-renewal notices to homeowners across the state, bringing its total policy count down to around 270,000. This process is not merely administrative; it reflects a broader push to restore balance in a sector battered by economic pressures, natural disasters, and legislative changes.
For homeowners receiving these non-renewal letters, the situation may feel alarming. With the clock ticking—Florida law mandates that clients have roughly a year to secure alternative coverage—the urgency to find a new insurer becomes paramount. As these displaced clients turn to insurance brokers for assistance, the insurance landscape in Florida is evolving, requiring brokers to adapt quickly and effectively to new market realities.
The Depopulation Strategy: A Closer Look
The non-renewal notices are part of Citizens' ongoing depopulation program, which aims to decrease its financial liabilities and encourage a healthier private insurance market. Michael Peltier, a spokesperson for Citizens, emphasized the progress that has been made: "I think this is the latest indication that the market is getting healthier. There’s more competition out there." However, this reduction in policy count comes with its own set of challenges as private insurers begin to re-enter the market, often with significantly higher premiums than those offered by Citizens.
Understanding the Transition
For many homeowners, the transition from Citizens to private insurers can be jarring. Florida law stipulates that if a private insurer offers a policy within 20% of the premium charged by Citizens, policyholders must accept it. While this regulation seems protective, it can lead to unexpected financial burdens. Citizens has historically offered lower premiums than many private carriers, meaning that homeowners might find themselves facing a steeper bill even before considering the 20% threshold. This is a crucial point that brokers must communicate to their clients.
The Financial Realities for Homeowners
As clients look for new coverage, it is important to understand the financial implications of moving from Citizens to a private insurer. Many homeowners may find their coverage inadequate or overpriced in the private market. For example, James Hembree, a resident of North Fort Myers, shared that he pays $3,200 annually for $75,000 of coverage on a home valued at approximately $150,000. This discrepancy highlights a common issue that homeowners face when transitioning to private insurance: the coverage-adequacy problem.
Moreover, the average homeowner's premium in Florida, which includes wind coverage, has climbed to about $3,815 as of April 2023. Despite some improvement, average premiums have fallen in 51 of Florida's 67 counties, illustrating a mixed bag of market conditions. With 21 new carriers entering the Florida market since recent legislative reforms, brokers now have more options to explore for their clients.
Legislative Changes and Their Impact
The recent legislative reforms aimed at stabilizing Florida's insurance market have played a significant role in shaping the current landscape. Changes such as the elimination of one-way attorney fees and restrictive assignment-of-benefit arrangements have encouraged private insurers to re-engage with the market. As these reforms take effect, the dynamics of the insurance industry in Florida are shifting, potentially benefiting consumers in the long run.
The Role of Brokers in the New Insurance Landscape
With the closure of the subsidized Citizens coverage window, brokers are positioned as vital resources for homeowners navigating this transition. They must manage client expectations concerning premium costs and coverage levels, particularly for older properties and those in coastal areas where the gap between Citizens’ rates and private market pricing is notably wide.
To effectively serve their clients, brokers should:
- Conduct thorough market research to identify the best available options.
- Educate clients about the differences in coverage and premiums between Citizens and private insurers.
- Assist clients in understanding the legislative changes that impact their coverage options.
- Prepare clients for potential increases in premiums, emphasizing the importance of adequate coverage.
Key Takeaways
- Citizens Insurance is reducing its policy count significantly, impacting approximately 45,000 homeowners.
- Florida law requires homeowners to accept private offers that are within 20% of their Citizens premium.
- Many homeowners may face higher premiums and insufficient coverage when transitioning to private insurers.
- Recent legislative reforms have introduced new private carriers into the market, providing more options for brokers and clients.
- Brokers play a crucial role in helping clients navigate the changing landscape and manage their expectations.
Frequently Asked Questions
1. What should I do if I receive a non-renewal notice from Citizens Insurance?
If you receive a non-renewal notice from Citizens Insurance, it is essential to act quickly. Florida law gives you approximately one year to secure alternative coverage. Begin by consulting with a licensed insurance broker who can help you explore your options in the private market. They can provide insights into the coverage differences and help you understand any potential premium increases you might face.
2. How does the 20% rule affect my insurance options?
The 20% rule in Florida law dictates that if a private insurer offers you a policy within 20% of your Citizens premium, you must accept that offer. This rule was designed to encourage homeowners to transition to private insurance. However, it can lead to higher premiums than what you currently pay, as Citizens typically offers lower rates. Make sure to review the details of any new policy carefully to ensure it meets your coverage needs.
3. What are the implications of recent legislative changes on my insurance premiums?
The recent legislative changes have aimed to stabilize Florida's insurance market by attracting more private insurers. This could lead to increased competition and potentially lower premiums in the long run. However, homeowners should be aware that initial premiums for new policies may still be higher than what they were paying with Citizens. It’s crucial to evaluate your policy options and shop around to find the best coverage at a competitive price.
4. How can I ensure I have adequate coverage after leaving Citizens?
To ensure adequate coverage after leaving Citizens, it’s important to work closely with your insurance broker. They can help you assess your property’s value and recommend appropriate coverage limits based on current market conditions. Furthermore, make sure to understand the specifics of any new policy, including deductibles, coverage limits, and additional benefits that may be included. Regularly reviewing and updating your policy as needed will also help maintain proper coverage.
Comments
Unprecedented Calm: The Atlantic Hurricane Season of 2026
The 2026 Atlantic hurricane season is on track to be the least active since 1941, raising questions about climate patterns, preparedness, and economic impacts.
Related articles
Popular in Home Insurance
- 2026 Sees Below-Average Severe Convective Storm Losses: What It Means for Insurance
- El Niño and Wildfires: Preparing for a Fire-Prone Future
- Young Affluent Collectors: The Underinsurance Dilemma in Luxury Investments
- Wisconsin Property Owner Sues City and Insurers Over Contamination Cleanup Costs
- Rising Catastrophe Risks: How Europe’s Insurers Are Adapting to Climate Change